To give yourself the peace of mind you deserve, trust USIC with your property insurance.
Protect your project in the event of hurricanes or earthquakes. Our policy is specifically designed for new projects that are in the construction or remodeling and alterations.
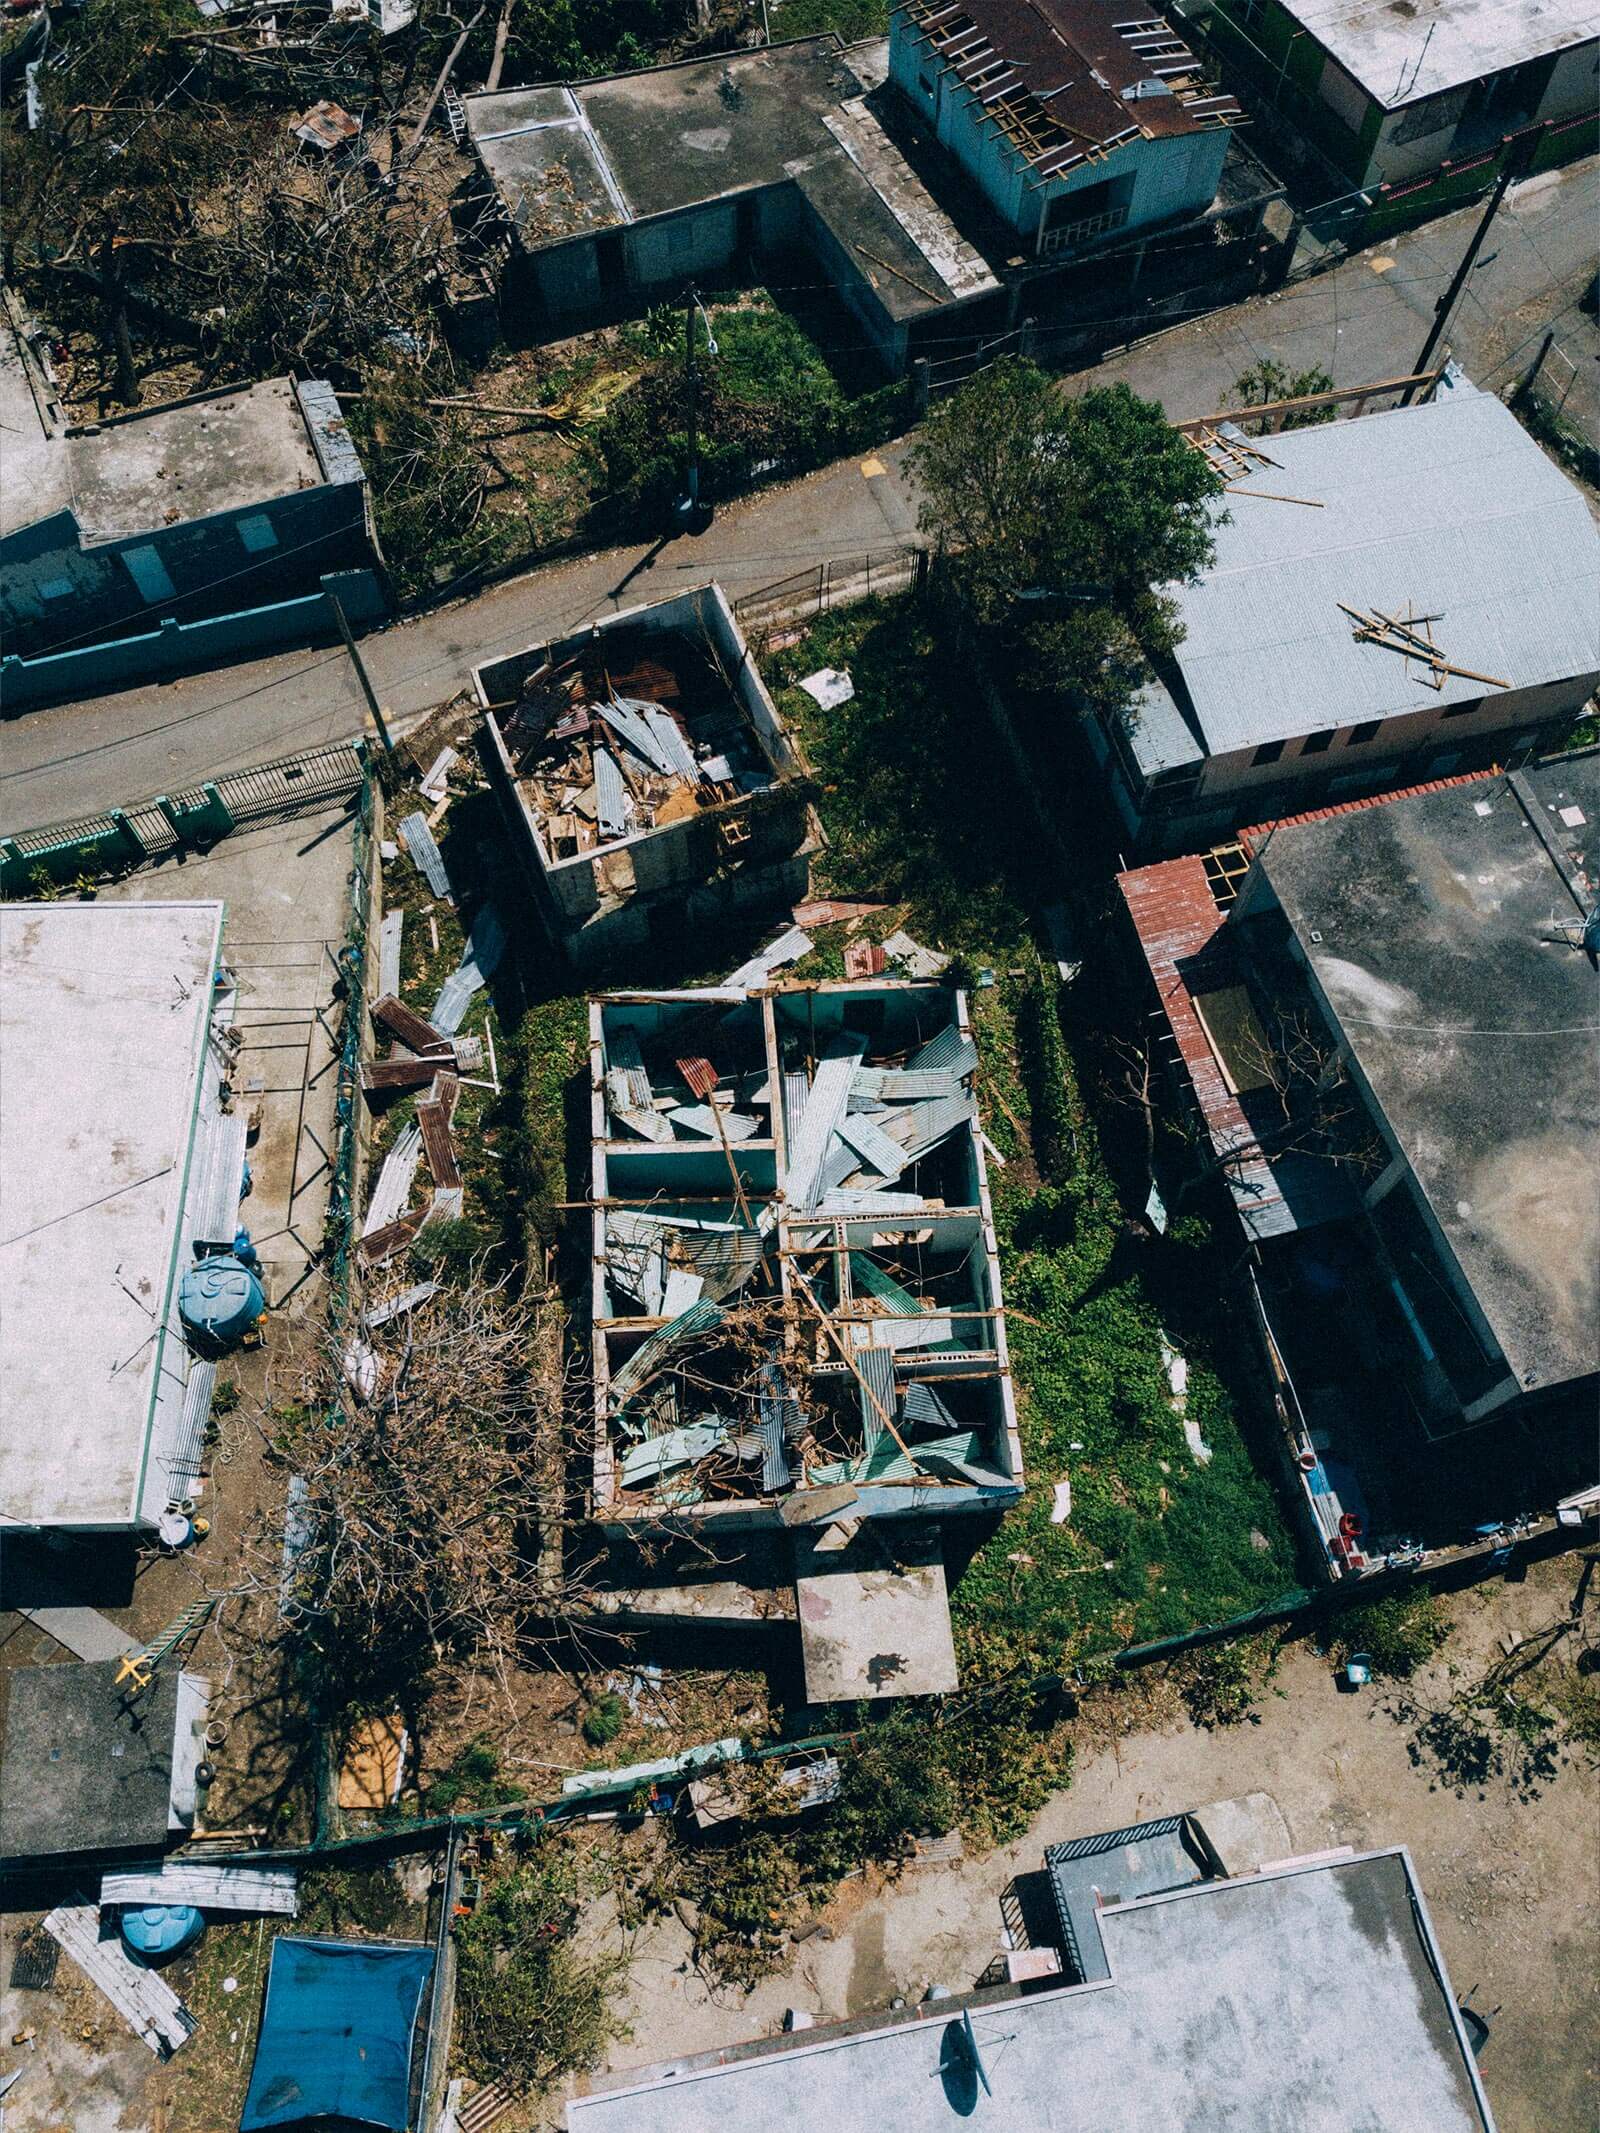
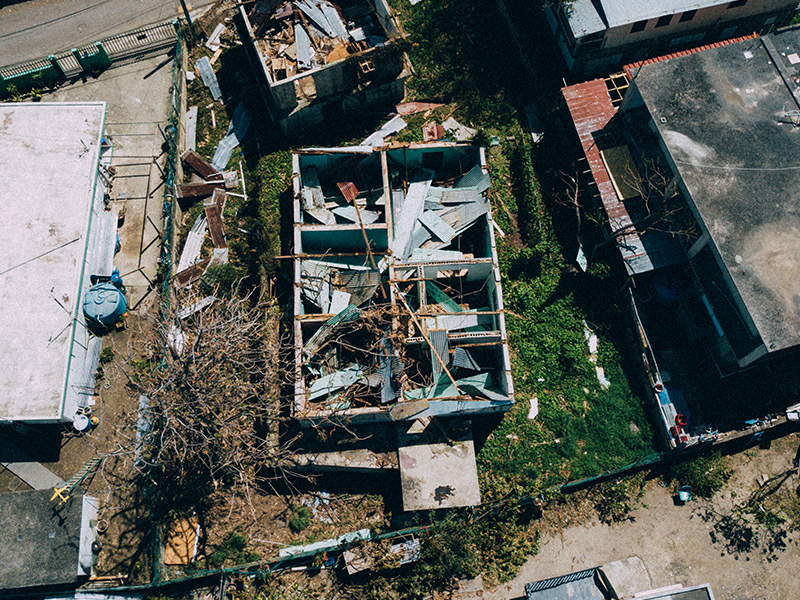
When you insure your property, you insure your family. Our Dwelling Policy (DP-1), also known as Hazard Insurance, provides compensation to the property owner and the mortgage lender for damages or losses caused by any of the insured hazards.
- Extended Cover: Hurricane, windstorm, or hail (deductible of 2% of the insured limit for concrete residences and 5% for mixed or wooden residences)
- Earthquakes (deductible of 2% of the insured limit for concrete, mixed, or wood residences)
- Fire ($250 deductible)
- Vandalism ($250 deductible from the insured limit; optional coverage for an additional cost)
- As an additional benefit, we include an applicable replacement cost endorsement if the property is insured for 80% of the replacement cost or more at the time of loss.
This policy is one of the most complete and robust we currently offer. Its broad coverage lets you protect more at an affordable price. The basic coverage includes protection for the structure with a minimum limit of $50,000, personal liability of up to $300,000 and $1,000 for medical expenses.
- Insured Risks
- Additional Coverages
- Personal property
- Additional endorsements
-
The main risks insured under this policy are the following:
- Hurricane or wind storm (2% deductible from insured limit)
- Earthquake (2% deductible from the insured limit)
- Fire ($250 deductible from the insured limit)
- Vandalism ($250 deductible; optional coverage for additional cost)
- Other insured risks
-
As part of the basic package, you get the following coverages:
- Refrigerated property: $600
- Grave Markers: $5,000
- Credit cards, electronic fund transfer card: $3,000
- Loss Assessment: $2,000
- Owner’s furniture: $3,000
- Lockset replacement: $1,000
- Fire Department services: $500
- Identity Fraud Expense: $5,000
- Flood (personal property): $3,000
- Endorsement of replacement costs: As an additional benefit, our policy includes an applicable replacement cost endorsement if the property is insured for 80% of the replacement cost or more at the time of loss.
-
You can extend your basic package for an additional premium to cover the contents of your residence. This includes the following:
- Money, bank notes, bullion, etc.: $500
- Securities, accounts, deeds, manuscripts, etc.: $2,000
- Watercraft, including their trailers and accessories: $2,000
- Trailers or semitrailers not use for watercraft: $2,000
- Theft of jewelry, watches, furs, stones, necklaces, among others: $2,000
- Theft of firearms: $3,000
- Theft of goldware, silverware, platinum ware, pewterware: $3,000
- Personal property on commercial premises: $3,000
- Personal property outside the premises for commercial use: $1,500
- Portable electronic equipment and accessories, on the premises and inside a motor vehicle: $2,000
- Electronic and portable equipment, on and off the premises of a motor vehicle, primarily used for business purposes: $2,000
- Essential emergency replacement clothing and toiletries purchases in case the insured is not able to access to the insured property due to a covered loss: $500
-
You can purchase the following endorsements for an additional cost:
- Personal Liability and Medical Expenses: We offer you protection in case of damage to other people’s property and personal injury to third parties with a maximum limit of up to $500,000 in personal liability and $5,000 in medical expenses.
- Home care: For an additional $30, we offer home emergency services such as plumbing, electricity, locksmithing and glazing, in the event of a fortuitous event to the secured property. For each service apply a benefit of up to $300 maximum per year policy.
- Endorsement to increase of credit card base limit
- Endorsement to increase of the basic limit of identity theft
- Inflation protector
- Personal injury endorsement (Personal Injury)
- What is a Builder’s Risk policy? + The Builder’s Risk Policy protects residential or commercial buildings and structures during construction or remodeling, as well as the equipment and materials used on the job site, in the event of a hurricane, earthquake, fire, theft, vandalism and other perils.
-
Who should get a Builder’s Risk Policy?
+
- Owners of commercial or residential buildings
- Construction or remodeling companies
- Contractors or subcontractors
- Architects or engineers involved in the project
-
What does the policy cover?
+
It covers loss of or damage to:
- The structure under construction
- Materials, equipment and supplies on the job site
- Property in transit or stored off-site (according to the policy)
- Damage from fire, vandalism, theft, explosion, storms and other perils
- How long does the policy last? + The policy covers the time the construction requires. If additional time or an increase in the project limit is needed, it can be handled through an endorsement. Note: The insured limit cannot be decreased, only increased.
- What are the perils insured under your Housing/Residential Property policy? + Hazards include windstorms, hurricanes, hail, earthquakes, fire or lightning, volcanic eruptions, smoke, and explosions.
-
What does the Hazard Insurance Policy (Dwelling DP-1) cover?
+
We cover the structure of your house in the event of:
- The main structure, attached structures (gates and gazebos, among others), and building materials that are used to repair or remodel the secured structure
- Losses that occur during the policy’s term
- Damages caused by an insured risk
- Which properties are eligible for the Dwelling and Residential Property Policy? + Residential building occupied up to 4 families located in Puerto Rico.
- What is the deductible applicable to the policy and how does the adjustment of the loss affect me? + The deductible is defined as the share (amount to be paid) of the insured in the loss caused by the covered peril. This value can be determined by a fixed amount or a previously agreed percentage. In the case of property policies for wind or hurricane hazard, it is 2% or $500 (minimum), whichever is greater. We recommend that you take a time for review your policy insurance declaration page and policy form to see conditions, limit of insurance and deductibles applicable.